From "The Pro Se Series" by Danny Hammond; Read More: THE PROBLEMS WITH OUR INABILITY TO STOP MORTGAGE FRAUD INVOLVES WRONGDOING BY MANY PEOPLE OVER A VERY LONG TIME- FOUR ELEMENTS ALLOWING FORECLOSURE FRAUD- "DEREGULATION" - "ACCOUNTABILITY"- "CONSEQUENCES" & "JUDGES"
THERE IS A NEW SPIKE IN FORECLOSURES, BUT I DON'T THINK IT IS FROM A ROUND OF NEW FORECLOSURES. I HAVE BEEN GETTING AN INCREASING NUMBER OF CONTACTS FROM BORROWERS LOOKING FOR HELP WHO HAVE EITHER BEEN IN COURT, STALLING WITH MOTIONS PRO SE, OR JUMPING INTO BANKRUPTCY OR ALL THREE SINCE THE 2010-2014 ERA.
I THINK THE VARIOUS BAD GUYS, WITH NO INTEREST IN THE LOAN ITSELF, ARE RUNNING OUT OF INVENTORY FOR HOUSES TO FORECLOSE ON AND THEN SELL TO THEMSELVES AT A 100% PROFIT.
THEY ARE READY TO TAKE ON THE FEW BORROWERS THAT HAVE BEEN FIGHTING BACK. THEY HAVE LEARNED BECAUSE OF THE FOUR FACTORS THAT ALLOW THEM TO WIN EVERY TIME WITH NO DANGER OF GETTING CAUGHT. WHAT ARE THE FOUR FACTORS THAT HAVE BEEN LETTING THEM GET AWAY WITH HOME MURDER?
DEREGULATION- ACCOUNTABILITY -
CONSEQUENCES & JUDGES
Deregulation of the Finance Industry:
It's funny, I think about the issue very often, but I don't talk about the deregulation of banking being the hottest trigger of the three top reasons that you and I lost our homes.
The reason that I say it is funny because the reason that I don't talk about deregulation much is that no one much wants to hear about it. However, I think it is the most wicked and flagrant method anyone could dream up for attaining the illegal theft of a house.
Non-judicial foreclosure has been ruled in 26 states to be constitutional, but judges decided this. Thus began the problem of granting Imposters and Fictitious Payees that we mistakenly call banks the easily abused tool of deregulation of the entire finance industry allowing them to greedily enrich themselves and those they employee by using your money from your bank account to engage in risky lending and ventures that make them rich if they bet right and make you poor if they bet right or wrong.
Our entire world history is just a series of regulating those handling our money when times are bad and then deregulating the finance industry when times are good because since they are rich they know how to make everyone rich and we should free them up to do it well. This happens over and over again.
Accountability of the Finance Industry:
Let's look at World War I, the Great War. After the financial collapse of 1890 the finance industry had trouble getting its act together. After the taxpayers financed the banking industry recovery things went nicely for a while and then old rivalries between autocratic rulers who really didn't know much about life or money began to squabble. New weapons, new inventions, new mobility made all of the people of the world feel as if anything could be accomplished. Governments accomplished the creation of the Great War, the war to end all wars. The taxpayers paid for it. The taxpayers also paid for the recovery from it.
After the recovery from World War, I, individuals (not government or bankers) invented more modern stuff people in America grew happier and richer and owned more stuff than they ever had. They bought homes and cars and radios, and flew as paid customers on airplanes. up until 3 days before I was born and then they could buy televisions and such too.
As always, in these good times as the numbers of people that remembered The Great Great War grew smaller and smaller and the ever-expanding new people that did not experience the Great Great War began to finance their purchases and invest in stocks.
Americans were now ready to make money, even when they were at work making money. People forgot about the Great War because millions of young men weren't being killed every year and they could fly commercially.
Even the bankers and the "Wall Street Scoundrels" were slowly replaced by the younger bankers and "Wall Street Scoundrels" who didn't remember the Great Depression either. Their industry was learning all over again the advantages of using OPM (Other People's Money like Danny Devito's character defined it) and relentlessly continuing to try to move over and get next to the commercial banks "blind trusts" which is my name for checking and savings accounts.
So, the United States government which is owned by the same taxpayers that keep paying off the losses by the expert bankers and rich people whom it seems we're not the smartest guys in the room, but they were persuasive. Once again talked the government into deregulating the banks and let the stockbroker investment banks and the commercial bank merge, plot, scheme and make bad bets. The US Finance and Investment industries broke millions of securities investors, except themselves for they did not bet their own money, and in the world in one day on
October 24, 1929

DESPERATION DID NOT WAIT LONG
|
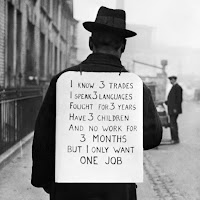
In a few short years as the economy heated up after World War I, there were several major policy decisions that concluded it was best not to regulate banks and stockbrokers because bankers and stockbrokers knew how to make the economy grow and because they were rich everyone believed they were smart and would help us all make money. So, once again, many regulations were eliminated (deregulated) to let the banks and Wall Street work their magic. Their magic brought on the Great Depression.
Simply put, the government had let the finance industry regulate itself.
|
THE CORNER OF BROKE BANK & BROKE BANK |
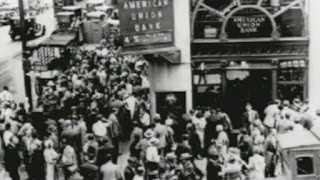
When you deregulate an industry that means you repeal the regulations that hold that industry in check. When you repeal regulations there is nothing for a regulator to do. No regulations! No regulators! No protections for the aforementioned US Taxpayers.
The government had thrown out all of the
rules. What kind of metaphor can we use to bring that image alive for us?
What if, just before the NFL decided the game of football wasn't exciting enough? There were too many rules. There was too much time taken away from actual football by the referees making so many calls. The fans wanted more action. So, let's say the NFL threw out all of the rules that had made football an organized activity for the last 100 years. Now, they had no rules so they could get rid of the game officials and save some money on salaries too. So, the very next Sunday the Kansas City Chiefs and Oakland Raiders run out of the locker rooms and onto the field. They look at each other and someone shouts "well let's get to playin'"?
They two teams can use whatever strategies they think up on the spur of the moment.
Dude! that would be a bad scene. See my article:
FRAUDULENT FORECLOSURE & DANNY HAMMOND'S MIKE SINGLETARY
OFFENSE FOR BORROWERS FACING MORTGAGE FRAUD
It was that kind of thinking that ignited the Wall Street Meltdown.
The term "Roaring Twenties" came about by the fact that the deregulated stock market had been on fire for more than eight years beginning of 1922. The total value of the stock market increased and everyone felt rich for eight years during the 1920s. Millions upon millions of investors lost everything and there was no stimulation for the lost economy. You see there was no FDIC in 1929. If the bank went broke, all of the depositors went broke. Except for about 1% of the people who were all ultra rich. Sound familiar? Even a little?
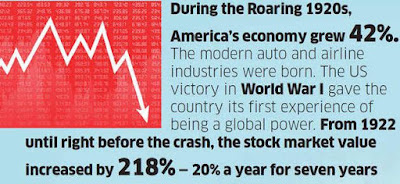
By the end of the year, the stock market free-fall was on its way to an 85% vaporization of wealth.
Are you sure it doesn't sound a little familiar? Are you better off than you were 3 years ago? That is the question the pollsters ask. Three years ago it was 2017. Ten years ago it was 2010. In 2010 we bottomed out. Augered In. Bit the Dust. Clicked out, this was the middle of the worst economy in close to 67 years (I will get to that.). The question is, "are we better off now than we were twenty years ago in 2001? I am not.
Folks, I am not. Someone, please tell me (there is a comment section at the end of this post, tell us all.) two things.
1. Tell us why the stock market is not artificially high. Interest rates have been near zero for ten years. The stock market appears safe to many people who really can't take adverse risks, but, you can't make money letting your retirement money sit in a bank. What other way is there to catch up now? Wall Street investments are the siren's song luring so many onto the rocks.
2. When economies are booming the stress of all this supposed cash should be inflationary. The Federal Reserve raises the interest rates during a hot inflationary economy to cool things off before inflation gets out of control. Donald Trump is hammering the Fed to lower rates to heat up the economy. Interest rates are hovering between 1% and 2%. Where does he think interest rates should be. Negative? Europe is close to going below 0%. Japan is near a 1% interest rate. China is stalling out. I am not the smart guy here. I want someone to really explain to me that everything is cool because our economy is booming. They tell us that unemployment is low (yes, but isn't it really true that is misstated because under-employment is way up?). There is no inflation pressure in the US whatsoever. Why did my economics professor teach me that a robust economy will drive inflation? Who are the idiots here? Am I one of them?
Interest rates have been at near ZERO for ten years. In my lifetime interest rates hovered between 8% to 10% for most of six decades.
Wall Street and their racketeering partners, as well as the six big banks (which I have been told control 70% of all of US wealth), have been making fortunes foreclosing on home loans that they have no interest in (they don't own them) for nearly 20 years. They don't pay off anyone with the proceeds of the foreclosure sale, because there is no one to pay. (I'm have explained that a dozen different ways on this blog. So I am not going to go through it again now.)
Below is the real story of the Great Depression. I am an optimist at heart. But, all of today's conversations tell me that we are picking up speed today and heading for the same abyss that we hurtled into in 1929. I just see no difference. The repeal of the Glass-Steagall Act in 1999 invalidated all of the statutes that gave us regulations and regulators. It put nothing in place to replace these safeguards. Dodd-Frank was supposed to fix that small oversight when it went into effect on July 21, 2010. Except it was gutted by Congress before they could get it on the truck.
The only good thing left was the Consumer Finance Protection Bureau and it was doing a great job of regulating. But, Trump sent Mulvaney to kill it. It only took Mick two days to cut the wires, but leave the body so no one would notice. I noticed. Did you? The CFPB is doing nothing but silly work. Don't bother sending your complaint there. Don't trust me. Google it. Mick and Trump killed and no Democrat or Republican even flinched. You should depend on yourself. That is the whole message of this blog. We can trust us.
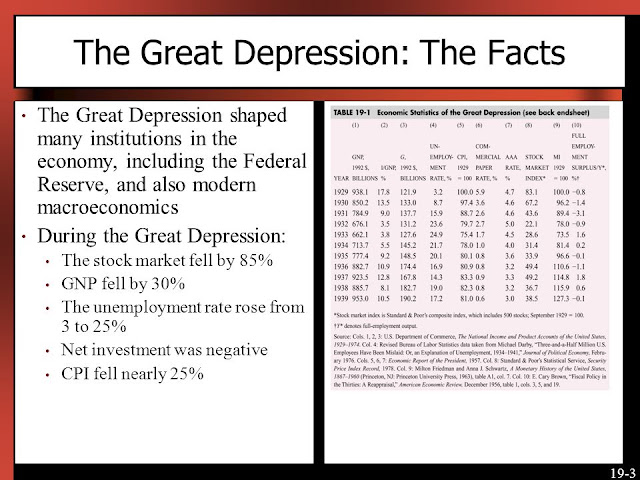
In fact, after the historic Wall Street collapse of 1929, some really smart guys got together and they decided that for much of the country's history banks were very tightly regulated
and scrutinized by regulators (the regulation referees watching the game closely). They put together a finance regulation bill called the Glass-Steagall Act of 1934. This set of regulations kept our economy safe for more than 67 years.
A couple of things were decided to be bad, as opposed to good. One is that there are basically there are two kinds of banks. Commercial Banks and Investment Banks.
Commercial Banks are where hard-working Americans deposited their money in checking and savings accounts and the commercial bank when regulated, made safe loans, but when they were not regulated they made not so safe loans. Much like sending elementary school kids outside the schoolhouse for recess but not sending teachers out to watch them because of course "the children could regulate themselves and would not get into mischief".
Here is where it gets creepy. Only a few well-known economists have tried to tell people that it is going to happen again here and soon. No one believes that. Many people think that the current economy is very safe. If you read this article, I urge you to stop listening to the band playing on TV, in the White House, at the federal reserve, and on Wall Street. The Democrat President Bill Clinton and a Republican Congress repealed the Glass-Steagall Act in 1999. The Act had kept the economy under control for 66 years. Eight years later the 2007-2008 Wall Street Meltdown nearly brought down the United States of America and the repercussions nearly brought down the whole damn world. Do Not take my word for it. READ. ASK. CHALLENGE.
By the early 1970s, it was no longer bad to think about supply-side economics (ONCE AGAIN). President Reagan really opened Pandora's box with his "Reagan-nomics "Trickle Down" theories.
CLICK HERE TO SEND US A "DETAILED" DESCRIPTION OF YOUR ISSUES